Advanced Micro Devices reported record third-quarter revenue of $13.4 billion on Tuesday, November 3, 2026, as demand for artificial intelligence chips and server processors continued to accelerate. Revenue increased 45% from a year earlier, while the company's data center business nearly doubled its sales to $8.5 billion.
The results exceeded Wall Street expectations and demonstrated AMD's growing position in the AI computing market. The chipmaker also issued an optimistic fourth-quarter forecast, predicting approximately $17 billion in revenue as production of its latest AI systems increases.
AMD reported adjusted earnings of $2.09 per share, up from $1.20 during the same quarter last year. Analysts had expected approximately $1.95 per share, making the earnings performance another positive development for the semiconductor company.
Data Center Revenue Jumps 97% as AI Demand Accelerates
AMD's data center division was the strongest part of its business during the third quarter. Revenue reached $8.5 billion, an increase of 97% from the previous year, reflecting demand for the company's EPYC server processors and Instinct AI accelerators.
The division accounted for approximately 64% of AMD's total quarterly revenue. Its growth demonstrates how rapidly the company's business is shifting toward infrastructure used by cloud computing providers and artificial intelligence developers.
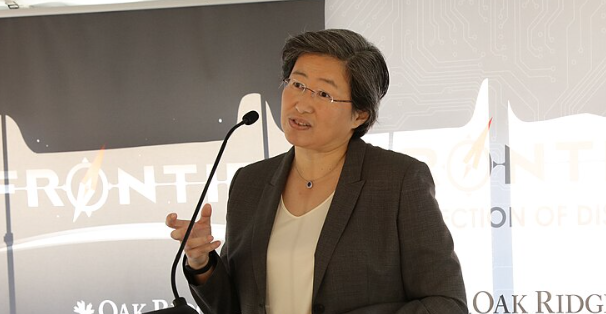
AMD CEO Lisa Su credited strong demand for both the company's central processing units and graphics processing units. In the earnings announcement, she said customer interest in Instinct and EPYC products continued to strengthen across the industry.
Server CPUs have become increasingly important as businesses expand their use of artificial intelligence. While GPUs perform the intensive calculations needed to train and run large AI models, CPUs manage many supporting tasks, including data processing, system coordination and cloud workloads.
The growing use of agentic AI could provide another source of demand. These applications use software agents to perform complex assignments, interact with other systems and complete multiple steps with limited human intervention.
Such workloads often require continuous access to computing resources. Companies operating AI agents at scale may need more server processors to manage virtual machines, coordinate tasks and support applications running around the clock.
AMD has positioned its EPYC processors to benefit from these requirements. The company is also expanding its portfolio of GPUs and integrated systems designed specifically for large AI data centers.
Helios Systems Strengthen Competition With Nvidia
One of AMD's most important new products is Helios, a rack-scale computing platform that combines processors, AI accelerators, networking and other components in a single infrastructure design.
The platform uses AMD Instinct MI450 Series GPUs alongside sixth-generation EPYC processors. It is intended to provide the computing capacity required for demanding artificial intelligence applications.
AMD confirmed that Anthropic, Meta, Microsoft, OpenAI and Oracle Cloud Infrastructure are running models and workloads on the first Helios systems. These early deployments represent an important step in the company's effort to expand beyond individual chip sales.
Nvidia remains a leading supplier of advanced GPUs and complete AI computing systems. Its hardware and software ecosystem has helped establish its position among major technology companies building artificial intelligence infrastructure.
AMD is competing by offering customers another source of high-performance computing hardware. The company hopes that its integrated platforms and open software approach will attract organizations seeking greater flexibility in their data center investments.
Helios also reflects a broader industry movement toward selling complete computing systems rather than individual processors. Large AI projects increasingly require coordinated combinations of CPUs, GPUs, memory, networking equipment and specialized software.
AMD expects production of Helios systems to expand during the fourth quarter. The company also plans to increase output of its next-generation EPYC processors, known by the code name Venice.
PC and Gaming Results Show Mixed Performance
Not every part of AMD's business experienced growth during the quarter. The company's combined Client and Gaming segment generated $3.7 billion in revenue, representing an 8% decline compared with the previous year.
The two businesses performed differently within that segment. Client revenue increased 7% to $2.9 billion, supported by demand for AMD Ryzen processors, particularly mobile chips.
Gaming revenue fell 40% to $773 million as sales of semi-custom products and graphics hardware weakened. The decline reflected a difficult comparison with the previous year and softer demand for certain gaming products.
The gaming business includes chips used in video game consoles as well as graphics products sold to consumers. Changes in console production schedules and demand for graphics cards can cause significant fluctuations in quarterly revenue.
AMD's embedded business delivered stronger results. Revenue increased 29% to approximately $1.1 billion, supported by sales to aerospace, defense, automotive, communications and industrial customers.
The mixed performance across these divisions illustrates AMD's changing revenue structure. Although personal computers and gaming remain important markets, data center products are now the company's primary growth engine.
Earnings Beat Expectations as Profitability Improves
AMD's financial results also showed stronger profitability. The company reported net income of $2.4 billion under generally accepted accounting principles, with diluted earnings of $1.46 per share.
That compared with earnings of 75 cents per share during the third quarter of 2025. AMD's reported net income included the effects of a $1.1 billion noncash charge related to changes in the value of warrants issued to certain customers.
Excluding specified accounting items, adjusted net income reached approximately $3.5 billion. Adjusted operating income rose 75% to $3.9 billion, indicating that profits increased faster than overall revenue.
AMD's adjusted gross margin was 56%, compared with 54% a year earlier. The improvement suggests the company benefited from a stronger product mix and higher sales of advanced computing products.
Reuters and other financial news organizations reported strong investor interest in the results, particularly the rapid expansion of AMD's AI infrastructure business. The company's shares increased in extended trading after the earnings announcement.
The results arrived during a period of considerable debate about technology industry spending on artificial intelligence. Investors have questioned whether companies investing billions in data centers will generate sufficient returns from those projects.
For chip suppliers such as AMD, however, the immediate effect of that spending has been rising demand for computing equipment. The longer-term outlook will depend partly on whether customers maintain their ambitious AI infrastructure plans.
Intel Competition and the Changing Server Market
AMD's performance also comes amid increasing competition with Intel in the server processor market. Both companies supply CPUs used in corporate data centers, cloud computing platforms and enterprise applications.
Intel recently reported a 78% increase in revenue from its Data Center and AI division, reaching approximately $7.3 billion. That growth reflects strong demand for server equipment even as other parts of the computer market face challenges.
The companies are pursuing opportunities created by the expansion of AI workloads, although their products and customer relationships differ. AMD has emphasized its EPYC processors and high-performance AI accelerators as major growth opportunities.
Competition between AMD, Intel and Nvidia will increasingly involve complete computing platforms, not just individual chips. Customers are evaluating energy efficiency, operating costs, software compatibility and the ability to expand systems over time.
AMD has also introduced new products intended to support AI applications running on personal computers and workstations. These include its Ryzen AI Halo platform and specialized systems capable of running large models locally.
Such products could eventually create additional revenue opportunities as businesses and consumers adopt more sophisticated AI software. Their commercial impact, however, remains less established than demand from major data center customers.
AMD Forecasts Another Strong Quarter
AMD expects fourth-quarter revenue of approximately $17 billion, with a potential variation of 3% above or below that figure. The midpoint would represent roughly 66% growth from the fourth quarter of 2025 and a 27% increase from the third quarter.
The company forecasts an adjusted gross margin of approximately 55%. Its outlook reflects expectations for continued demand for Instinct accelerators, EPYC processors and Helios computing systems.
AMD also expects its data center business to remain a major contributor to revenue growth in 2027. Management has expressed confidence that expanding AI infrastructure investments will support stronger sales over the coming years.
Those expectations depend on customer spending, manufacturing capacity and the successful introduction of new products. Competition and changing demand could still affect actual results.
For now, AMD's third-quarter earnings demonstrate a major shift in the company's business. Data center revenue has become the dominant source of sales, and its expanding AI product lineup is helping drive record financial performance.
The next important test will come in the fourth quarter, when AMD expects a substantial increase in revenue as Helios and Venice production expands. Investors will be watching whether the company can meet that forecast while maintaining profitability and competing for a larger share of the rapidly growing AI infrastructure market.