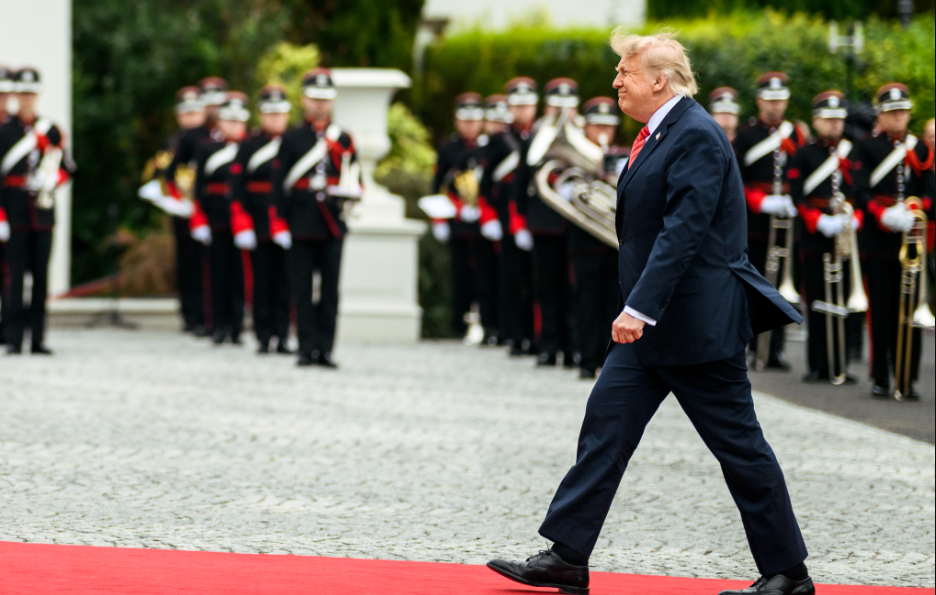
President Donald Trump made two large stock sales in July, disposing of shares in Amazon and Microsoft valued between $5 million and $25 million each. Both transactions occurred on July 20 and were disclosed in the president’s latest financial filing.
These transactions were disclosed as part of the president's financial reporting requirements, though they occurred during a period when he supports restrictions on lawmakers trading stocks. Trump endorsed the Stop Insider Trading Act, which was passed by the House in July.
The legislation would prohibit members of Congress, their spouses and dependent children from purchasing individual publicly traded stocks. It would not apply to Trump or Vice President JD Vance. The measure would also allow lawmakers to keep stocks they already own while requiring advance notice before certain sales.
The House passed the bill by a vote of 232-198 on July 22. The measure was later received by the Senate but had not become law as of September 22.
Trump’s July disclosure showed more than 700 stock sales and more than 440 purchases. The combined reported value of the transactions ranged from about $79 million to $270 million because federal disclosure forms report values in ranges rather than exact amounts.
Trump’s broader financial disclosures show income from his business network and cryptocurrency ventures. His previous annual disclosure reported more than $2.2 billion in income from businesses and investments during 2025, including about $1 billion connected to cryptocurrency ventures, according to The Guardian.
The White House has said Trump does not personally direct the individual stock transactions. Spokesperson Davis Ingle said the investments are held in discretionary accounts managed by outside financial institutions and that neither Trump nor members of his family can control individual purchases or sales.
Meanwhile, a separate legal battle is underway involving X Strategies, a political consulting firm that manages several prominent Trump-related social media accounts. The company maintains the Trump War Room and Team Trump accounts on X and helps manage the president's TikTok presence.
X Strategies filed a federal lawsuit against co-founder Derek Utley in the Southern District of Florida. The company accuses him of embezzling millions of dollars and using company money for gambling and personal expenses. Public court records show the case was filed on September 18.
Utley was a founding member of X Strategies alongside Alex Bruesewitz, who has become an outside adviser to Trump and an influential figure in the president's online operation. Utley served as the firm's chairman and chief financial officer and had extensive access to its bank accounts and financial records, according to the complaint.
The lawsuit alleges that Utley embezzled at least $5 million between 2021 and 2026 by disguising personal spending and transfers as legitimate business expenses. The allegations include claims that company money was used for luxury vehicles, designer clothing, jewelry, first-class travel and gambling.
The gambling allegations involve especially large amounts. X Strategies claims that Utley spent about 200 days at the Seminole Hard Rock Hotel & Casino in South Florida during 2025. The lawsuit alleges that he lost about $29 million while winning more than $26 million on slot machines during that period, producing a net loss of roughly $3 million.
Those figures are allegations made by the company and have not been established by a court.
The alleged scheme came to light after X Strategies hired Michael Seifert as its president. According to the lawsuit, Seifert noticed that the company had millions of dollars less cash than its reported revenues suggested it should have.
A key moment came when a third party reported that Utley had made an urgent call from a Las Vegas casino while highly intoxicated and requested a wire transfer. He allegedly claimed the company needed the money to make payroll the following morning. The lawsuit alleges that he had actually suffered a large gambling loss and wanted additional money to continue betting.
The incident led to a deeper review of the company’s finances. The lawsuit alleges that investigators discovered suspicious transactions and payments to Utley.
Utley initially denied taking money but later admitted to Seifert that he had stolen millions of dollars, according to the lawsuit. Because the statement is contained in X Strategies' complaint, it remains an allegation rather than an established fact.
Utley stepped down as chairman and chief financial officer in April but remained employed for a short time.
The firm claims he later submitted fabricated medical records while seeking six months of paid medical leave. According to the complaint, the medical provider told X Strategies that the documents were not genuine. The company later fired Utley.
Utley has denied the allegations. He told Politico that he disputes the claims in the complaint and intends to address them through the legal process.
The lawsuit includes claims of civil racketeering, civil theft, fraud and breach of fiduciary duty. No court has determined that Utley committed the alleged misconduct.
The lawsuit against Utley is separate from Trump's personal financial disclosures. However, both developments emerged as financial activity involving public officials and Trump-linked organizations continued to receive public attention.